debt snowball vs avalanche calculator which is better
Compare the psychological momentum of the Snowball against the mathematical interest savings of the Avalanche.

Marcus Vance
Certified Financial Planner • Published Oct 18, 2024

When deciding debt snowball vs avalanche calculator which is better, the answer depends on whether you prioritize quick psychological wins or mathematical interest savings. According to landmark behavioral research from Harvard Business Review, consumers who use the Debt Snowball method—paying off smallest balances first—are significantly more likely to eliminate their debts completely due to the motivating momentum of early victories. Conversely, the Debt Avalanche method—targeting highest interest rates first—saves the maximum amount in compounding finance charges. Using SphereBudget’s Debt Payoff Calculator, you can simulate both strategies side by side to discover which roadmap fits your personality and accelerates your debt-free date.
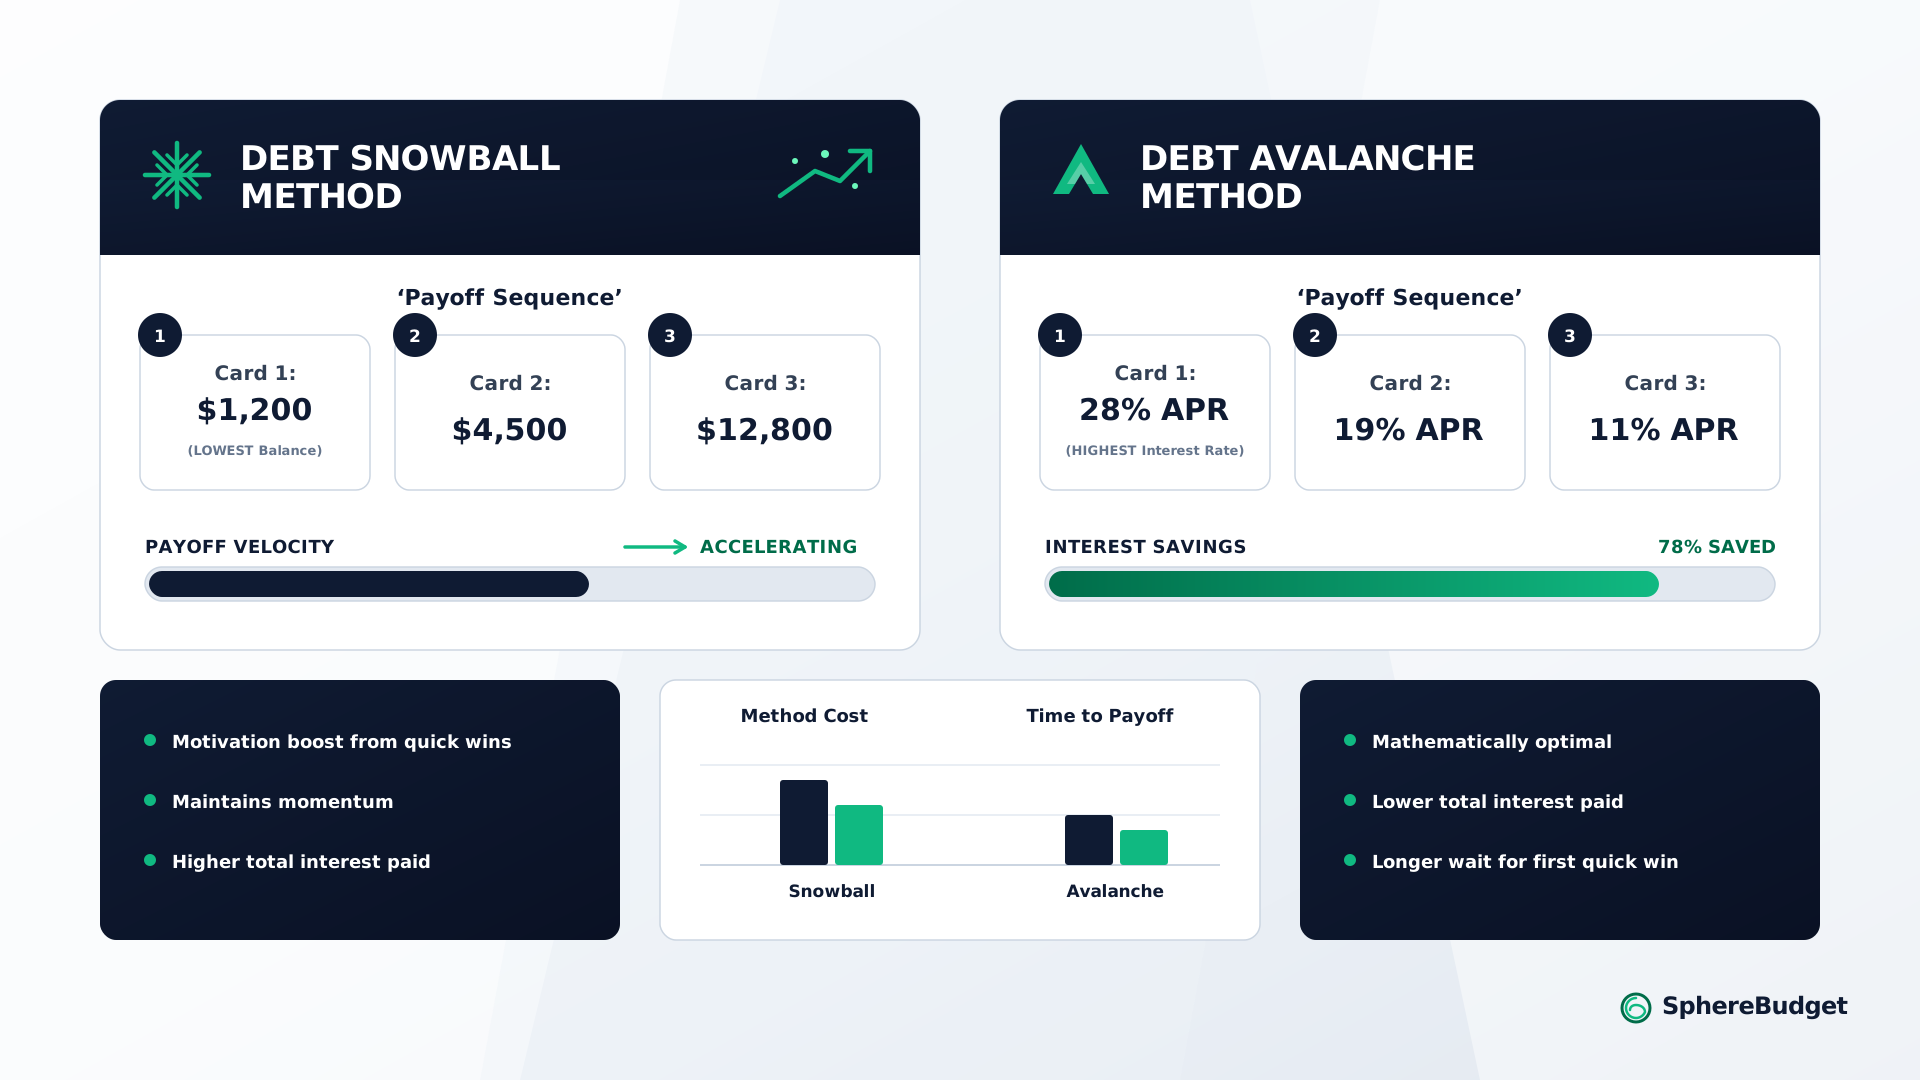
The Core Difference: Mathematical Efficiency vs. Psychological Momentum
The Debt Snowball: Lists debts from smallest balance to largest balance regardless of interest rate. Knocking out small accounts quickly produces dopamine wins that keep you motivated.
The Debt Avalanche: Lists debts from highest interest rate to lowest interest rate. Eradicating high APR debt first minimizes total interest paid over the life of your loans.
5 Practical Steps to Eliminate Debt Using Snowball or Avalanche
- Step 1: Document Every Debt Account: Input current balance, APR, and minimum monthly payment into SphereBudget.
- Step 2: Commit to Paying Minimums on All Non-Target Accounts: Prevent late fees and protect credit scores.
- Step 3: Choose Your Primary Acceleration Method: Select Snowball for motivation or Avalanche for interest savings.
- Step 4: Direct Every Available Dollar Toward Your Target Debt: Funnel budget surpluses to your priority balance.
- Step 5: Roll Over Payments as Debts Clear: Add the freed-up payment to the next debt on your list.
Debunking the Pure Math Myth: Why Psychological Adherence Beats Theory
The best debt payoff strategy is the one you actually stick with until the end. If targeting a large high-interest loan leaves you feeling discouraged after six months, the Snowball's quick victories will keep you in the game.
Pro Tip: Deploy the "Snowflaking" Strategy for Fast Principal Reduction
Make micro-payments of $15, $25, or $50 immediately whenever you save money on groceries or sell an item online. These frequent payments reduce the daily compounding balance on high-APR cards.
Simulating Your Debt-Free Date with SphereBudget
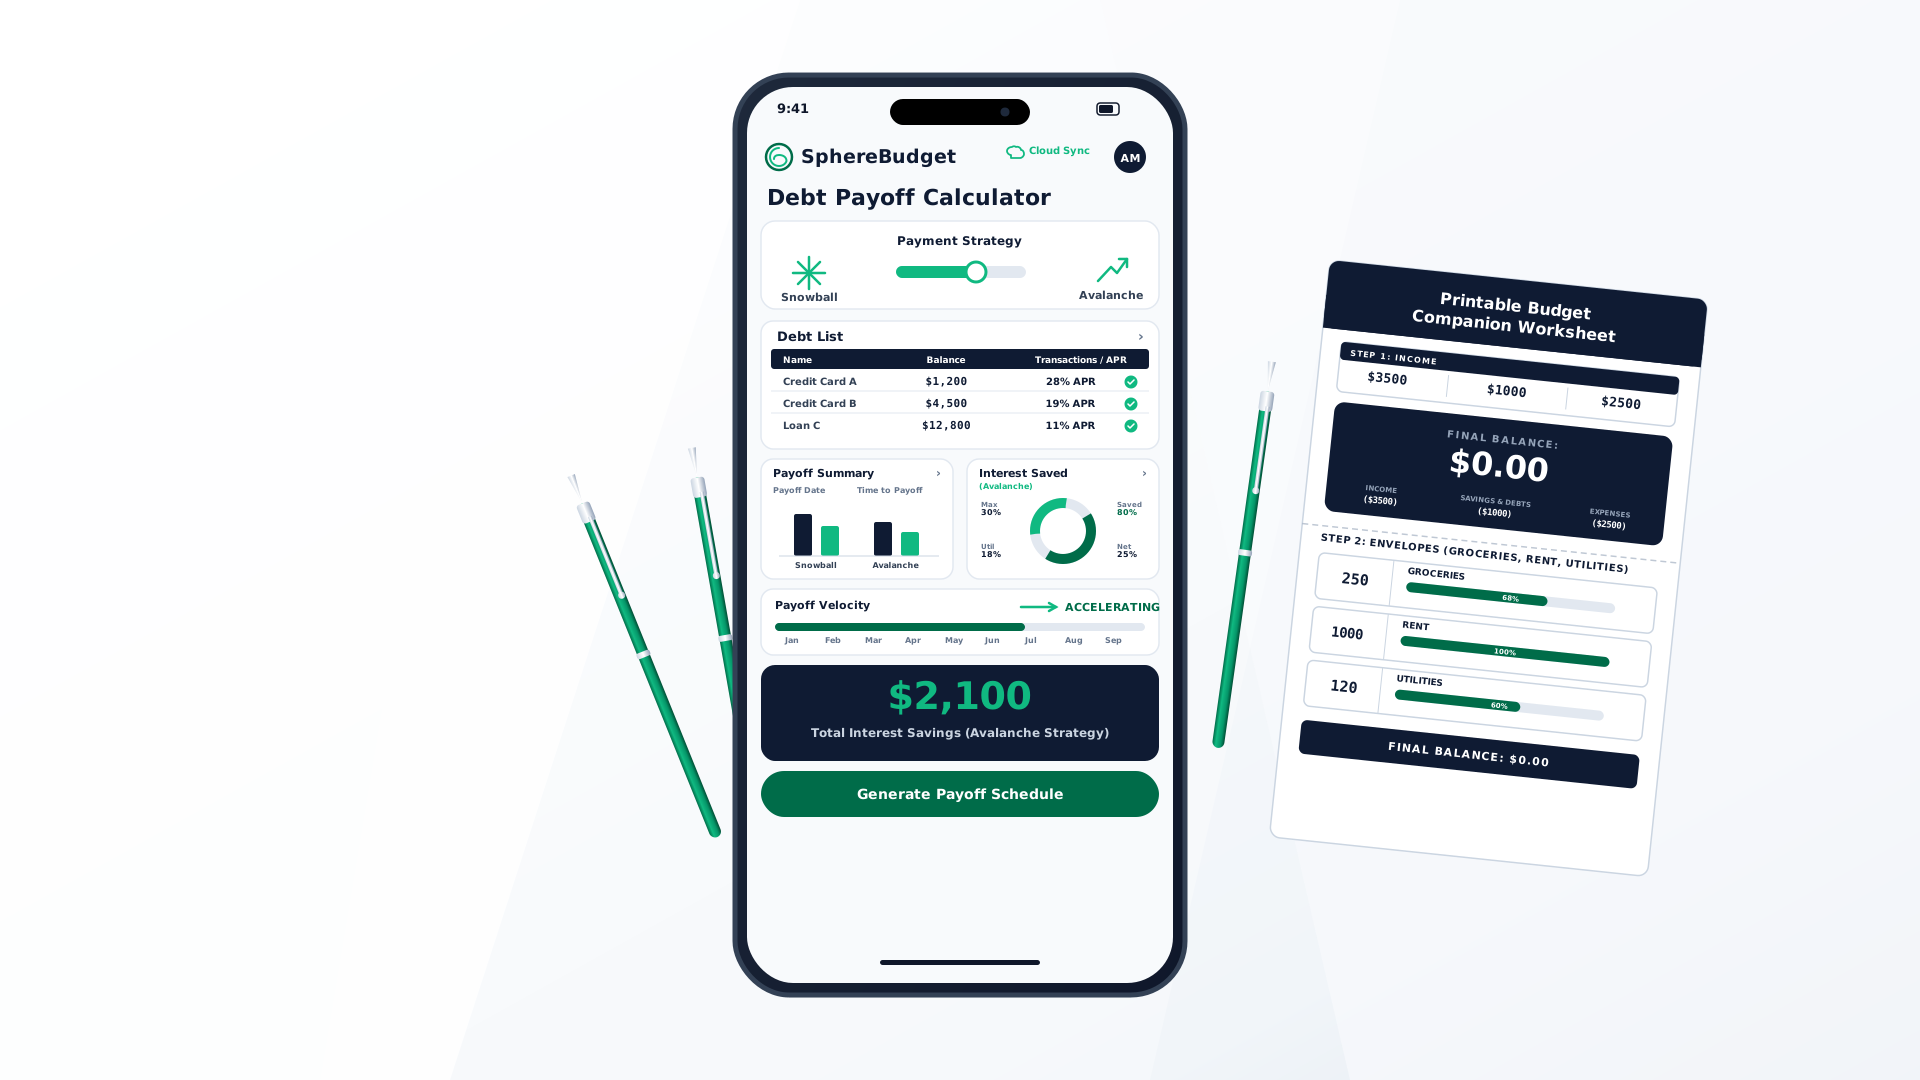
SphereBudget’s built-in Debt Payoff Calculator provides a private, ad-free environment to model payoff schedules, compare extra payment amounts, and watch your debt-free milestone move closer.
This is educational guidance – consult a CFP for personalized advice.
Debt Payoff Calculator
Simulate Snowball vs Avalanche payoff schedules and see how much interest you eliminate.
Written by Marcus Vance
Senior financial strategist specializing in behavioral economics and wealth preservation frameworks at SphereBudget.
In This Article
Related Reading

how to make a budget when you live paycheck to paycheck
Learning how to make a budget when you live paycheck to paycheck begins with one immediate tactical shift: you must budget the exact cash currently sitting in your bank account today.

zero based budget spreadsheet free printable
A zero based budget spreadsheet free printable is an intentional money management framework where your total net income minus all allocated expenses equals exactly zero.

50 30 20 budget rule calculator for beginners
A 50 30 20 budget rule calculator for beginners divides your total net take-home pay into three simple, proportional spending categories.